Impacting Your UBPR Through Business Development
Smarter Deposits, Stronger Relationships, and the Connection to Bank Performance
Is Your Business Development Process Designed to Impact Your Bank’s UBPR?
Are the activities your business development team performs every day designed to influence the financial measures your leadership team wants to improve?
Bank presidents and leadership teams regularly review loan growth, deposits, net interest margin, noninterest income, and efficiency. These measures help tell the story of how a bank is performing.
But behind those numbers is another question: Does your business development process equip and hold your team accountable for developing the relationships and creating the client value needed to influence those results?
General sales training, product knowledge, and relationship skills provide a foundation. They help bankers understand how clients finance operations and manage cash. But if the bank’s goal is to improve a specific financial measure, leadership must go a step further: identify the client relationships, banker skills, and repeatable activities most closely connected to that goal.
Priority financial measure → Targeted skill development → Consistent business development process → Leadership accountability
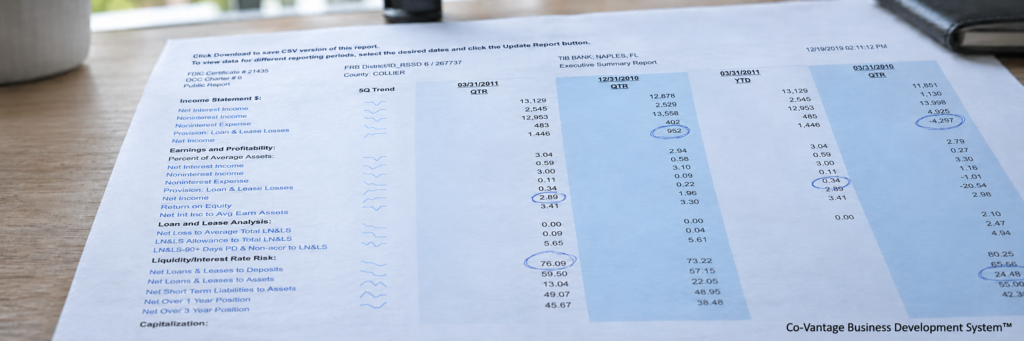
Your Uniform Bank Performance Report (UBPR) helps you understand where your bank stands and how it compares with peers. Your strategic plan establishes where you want to go. A strategic business development process helps answer the question that follows: How are we going to get there?
When you leave a planning session with goals for growth and profitability, an important part of the answer is already within your team. The opportunity is to align what bankers do every day with the relationships your bank wants to develop and the financial outcomes leadership wants to influence.
Research supports paying attention to that connection. A study in Industrial Marketing Management examined 816 salespeople and sales directors across 30 business-to-business sales organizations. It explored how sales strategy translates into individual selling performance, including the role of customer orientation and value-based selling. Though not a banking study or proof of a specific UBPR result, it reinforces a practical question: How does the strategy developed at the leadership table become the way your team sells?
If improving net interest margin is a goal, bankers need more than general product and pricing knowledge. They need a process for connecting industry trends to a client’s financial challenges, demonstrating how the bank can help, and discussing the value of the overall relationship before the conversation centers on rate.
The objective is to create and capture client-centered value. Creating value means bringing relevant insights, exploring their financial implications with the client, and helping the client evaluate a path forward. Capturing value means earning an appropriate return through pricing and the overall relationship because the client understands the value being delivered. Better conversations do not guarantee a higher margin, but can support pricing discipline.
If growing deposits and noninterest income is a goal, bankers need a process that connects industry insight to a client’s liquidity and financial needs, earning the opportunity to discuss operating deposits and appropriate services. Operating deposits may affect funding mix and net interest income, while service fees may contribute to noninterest income.
If improving productivity is a goal, bankers and leaders need a way to identify the right prospects, qualify opportunities, recognize stalled pursuits, and agree on meaningful next steps. The goal is to spend more time advancing relationships that fit the bank’s strategy and less time pursuing opportunities unlikely to move forward.
Each priority requires a different emphasis. The stronger the connection between the desired outcome, the skills being developed, and the process being managed, the more deliberately a bank can evaluate the return on its business development investment.
The question for leadership is where to begin. Start by examining the conversations your bankers are having—and what those conversations are accomplishing.
Are Your Bankers Effectively Selling Your Competitors’ Products?
Over the course of my career, I have interviewed hundreds of CEOs and decision-makers about their experiences with salespeople, including commercial bankers. A consistent theme emerges: A banker may earn the meeting, but the business owner often receives little value from the conversation.
The banker arrives and asks, “Tell me about your business.” The conversation then moves to the bank’s history, its commitment to service, and the capabilities of its products. Meanwhile, the business owner is left to explain the company, its industry, and its challenges.
Questions are an important part of any business conversation. But when the banker arrives expecting the client to provide the education, the client may reasonably wonder what the banker has brought to the meeting.
If your banker put on a polo shirt with your fiercest competitor’s logo and used the same sales process, could they just as easily sell that competitor’s products?
The decision-makers I have interviewed describe a familiar process across competitors: asking discovery questions, discussing product capabilities, and attempting to create value in much the same way. Differentiation requires a different business development process.
Research supports the importance of bringing a different perspective to the conversation. In LinkedIn’s 2022 State of Sales research, 89% of surveyed B2B buyers said they were more likely to consider a brand if a seller changed their way of thinking. This research spans B2B markets rather than banking alone, but underscores the opportunity to offer a perspective the buyer finds useful.
In my earlier research summary, I cited Selling to the C-Suite by Nicholas Read and Stephen Bistritz for a striking contrast: 24% of salespeople demonstrated a meaningful understanding of the executive’s business, while 88% demonstrated strong knowledge of their own products and services. Knowing the product is essential, but it does not by itself demonstrate an understanding of the client’s business or create a reason to change. [Figures require verification against the original book before publication.]
When a prospective client sees no meaningful difference in the value being delivered, what reason do they have to undertake the effort and friction involved in moving an established banking relationship? A comparable product or a pleasant conversation may not be enough to make a change worthwhile.
The opportunity is to change the starting point. A strategic banker comes prepared to discuss where the client’s industry and the banking industry intersect—and how trends at that intersection may affect the client’s business and key metrics.
The value is not simply in discussing cash flow, a financial statement, or an industry trend. It is in bringing a banking lens to the conversation: helping the client consider how a trend may affect the business, how a bank might view the resulting financial risks, and what potential mitigants the client may want to explore.
For bank leadership, the question becomes: Are we equipping bankers to explain our products—or to create a reason for clients to value a conversation with our bank? When bankers consistently connect relevant industry insights to the client’s financial risks and opportunities, they create an opportunity to differentiate before the discussion becomes a comparison of rates and product features. That can open the door to a broader conversation about operating deposits, treasury services, and the full relationship.
Smarter Deposits, Stronger Relationships
Is your business development process helping clients make smarter decisions about their deposits—and giving them a reason to build a stronger relationship with your bank?
Smarter deposits begin with a more strategic conversation. A banker brings relevant industry research and a banking perspective to the client, then explores how emerging trends may affect the company’s financial position, risks, and future needs. The client gains a perspective on how to position active and idle funds in support of the business.
Stronger relationships develop when that value creates an opportunity to serve more of the client’s financial needs over time. The goal is to earn a fuller banking relationship—one that may include operating deposits, lending, treasury services, and other appropriate solutions.
For the bank, this raises another important question: Are we attracting new dollars and developing new relationships—or paying more for balances we already hold?
Are You Growing Deposits—or Paying More for the Same Dollars?
A growing deposit balance does not always tell the full story. When rates change, a bank may retain an existing relationship by paying more for funds already on its balance sheet. That decision may be appropriate. But if higher-cost balances replace lower-cost balances without bringing in new funding, the bank’s cost of funds can increase without a corresponding increase in deposits.
The opportunity is to develop a process that helps bankers create a reason for clients to bring net-new active and idle funds to the bank, while also strengthening existing relationships. That requires more than asking for deposits or offering a competitive rate. It requires bankers to develop the skills to research a client’s industry, identify relevant trends, connect those trends to potential financial risks and opportunities, and lead a conversation the client considers valuable.
A Strategic Conversation Creates a Reason to Move
A business owner may have active funds supporting payroll, receivables, and daily operations, along with idle funds reserved for future needs or investment. Those balances may be held across several institutions. Moving them can involve effort, uncertainty, and disruption.
A study using data from 1,326 U.S. small firms found that seeking credit outside a primary financial relationship was less likely when the primary institution was a nearby bank associated with quality service and other business or personal connections. The study examined borrowing rather than the movement of deposits, but illustrates why an established relationship can be difficult for a competing bank to displace.
If your bankers are asking the same questions and presenting capabilities similar to the incumbent bank, what reason does the client have to accept the friction of moving?
A differentiated process starts earlier. A banker arrives with an understanding of the client’s industry and a banking perspective on trends that may affect the business. Together, the banker and client explore how those trends may influence the company’s financial position, liquidity needs, and key metrics—and how a bank may view the associated risks and potential mitigants.
Research by Bonney and colleagues in Industrial Marketing Management examined when buyers consult existing and competing salespeople before a purchasing decision formally begins. Across four scenario-based studies involving 324 purchasing managers, the researchers found that the likelihood of consulting an incumbent or non-incumbent salesperson varied with the circumstances of the business problem. The research concerns organizational purchasing rather than banking, but points to an opportunity: a banker may contribute a useful perspective before a client has decided to review its banking relationships.
The value to the client is a more informed perspective on how to position funds for current operations and future needs. For the bank, the discussion creates an opportunity to understand where those funds are held and what would need to happen to earn a larger share of the relationship.
Build the Skills and Process to Earn the Relationship
A strategic conversation cannot depend solely on the natural ability of a few experienced bankers. Leadership can develop it as a repeatable business development process. Bankers need to know how to find credible industry information, identify a trend relevant to a particular client, and translate it through a banking lens. They must be able to discuss its potential financial impact, explore the client’s perspective, and follow up with information that advances the conversation.
Leaders can then coach and inspect the process: Did the banker bring a relevant insight? Did the client gain a perspective worth discussing? Was the follow-up useful? Is there a mutually agreed next step? This is how skill development and accountability connect the bank’s deposit strategy to the conversations taking place in the market.
Measure New Dollars and Relationship Value
Are our bankers creating enough differentiated value for clients to consider moving funds from another institution—or are we primarily competing for balances through rate?
Alongside total deposit growth, leadership can examine net-new funds, changes in existing-client balances, funding cost, and the development of operating relationships. That helps distinguish new money from internal balance migration and supports a clearer view of the economics.
A strategic conversation may also uncover opportunities to serve more of the client’s needs over time. Appropriate treasury, payment, and credit services become part of a broader relationship discussion, informed by the client’s situation. For the bank, that relationship may contribute deposits, net interest income, and noninterest income; for the client, it should provide value that justifies the effort of establishing or expanding the relationship.
The goal is smarter decisions for the client, new dollars for the bank, and a stronger relationship that creates value for both.
Are You Developing the Full Value of Each Relationship?
Banks often encourage cross-selling by setting goals for referrals or the number of products per client. Those measures can be useful, but they do not tell the whole story. A client may have several products with the bank and still rely on another institution for its most important financial decisions. Another client may have one relationship today but significant potential as the business grows.
Are your bankers developing the full value of the relationship for both the client and the bank?
For the client, value might mean a more efficient way to collect payments, better visibility into cash flow, financing that supports a growth plan, or a conversation that helps an owner prepare for a financial decision. For the bank, a broader relationship may contribute loan income, deposit funding, treasury fees, and opportunities to serve the client over a longer period. Its actual lifetime value also depends on pricing, credit risk, cost to serve, and how long the relationship lasts.
The Federal Reserve’s analysis of the 2023 Small Business Credit Survey found that more than two-thirds of applicants to large or small banks cited an existing relationship with the lender as the most significant reason for applying there. It suggests that the relationship a bank builds before the next financing need can matter when the client decides whom to call.
Rather than beginning a relationship review with “What else can we sell this client?” begin with “What do we understand about where this business is going, and where might its financial needs change?” That question can lead to a relevant introduction to treasury management, another specialist, or a future planning conversation. Cross-sell becomes a way to serve a need the banker has uncovered, while potentially strengthening the economics and duration of the relationship.
Is Accountability Built Into the Process?
A business development strategy has little practical value if it remains in the strategic plan. It must become visible in how bankers prepare, engage clients, follow through, and how leaders coach the team.
Does your organization inspect what it expects—at every stage of the relationship?
That does not mean measuring activity for activity’s sake. It means establishing what good execution looks like and reviewing whether the work is creating value. A banker may be expected to research a targeted client, identify an industry issue, prepare a relevant point of view, and explain why the conversation matters to that business. After the meeting, accountability may include documenting what was learned, delivering a useful follow-up, involving the right internal partners, and agreeing on the next step with the client.
The process continues after a relationship is won. Is the bank checking whether the proposed solution is working? Are bankers revisiting the client’s goals and identifying changes in the business? Is the relationship developing in a way that creates value for the client and an appropriate return for the bank?
In Harvard Business Review, Jason Jordan and Robert Kelly reported research associating a formal sales process with stronger revenue performance. Their work offers a reason for leaders to examine how consistently their process is defined and managed; it does not establish that a particular process will produce a specific result at any given bank.
The quality of leadership coaching matters as well. A study of 1,246 sales representatives in a pharmaceutical organization found that managers’ coaching skill was associated with their teams’ sales goal attainment. More frequent coaching was not beneficial when coaching skill was low. The lesson is to make coaching purposeful: clarify expectations, observe the work, give useful feedback, and help bankers improve.
Accountability connects the bank’s investment in strategy and training to the work performed afterward. It gives leaders a way to see whether skills are being applied, where bankers need support, and whether the intended results are beginning to emerge. That makes it possible to assess and improve the return on the investment over time.
Connect the Activity to the Outcome
Most banks measure business development activity. Calls, appointments, referrals, and proposals all have a place. They become more useful when leadership can connect them to a clear financial purpose.
If the goal is stronger deposit relationships, leaders might review whether bankers bring relevant industry insights, identify where operating accounts are held, and involve treasury partners when there is a relevant need. If the goal is improved pricing discipline, leaders might examine whether bankers can explain the value of a proposed relationship before discussing price. If the goal is better productivity, leaders might review opportunity quality, time in the pipeline, and what prevents qualified prospects from reaching a decision.
These are leading indicators: activities and milestones the bank can observe and coach before the full financial outcome appears. The UBPR provides a view of broader financial results. Together, they help leadership examine whether the bank is building the capabilities and relationships needed to support its goals.
The connection should be tested, not assumed. Changes in margin, deposit mix, noninterest income, or efficiency can reflect interest rates, market conditions, credit decisions, funding costs, and many other factors. Business development is one part of the picture. Establishing a baseline and reviewing results over time gives a bank a more meaningful way to evaluate progress.
Questions for Your Leadership Team
- Are our bankers’ daily activities and skills aligned with the specific financial outcomes we want to influence?
- Can our bankers demonstrate client-specific value that differentiates our bank and supports an appropriate return?
- Are we developing the full relationship—including operating deposits and relevant services—or focusing primarily on individual transactions?
- Do our leaders inspect, coach, and hold the team accountable for creating value from targeting through closing and beyond?
The answers may reveal an opportunity to build a more intentional process—one that connects the bank’s financial priorities to the skills, conversations, and leadership practices required to pursue them.
Your UBPR helps show where your bank stands. The process your team executes today can help influence where it goes next.
About the Co-Vantage Business Development System™
Larry works with organizations to create and capture client-centered value through his Co-Vantage Business Development System™. The system connects strategic targeting, sales intelligence, client value, and sales and leadership development to help banks align the relationships they pursue, the insights bankers deliver, and the accountability leaders provide with the financial measures they seek to influence.
About Larry Young
Larry Young is the founder of Boiling Frog Development and a business development consultant, speaker, author, and sales and leadership trainer. Drawing on 22 years in commercial and agricultural banking, including his experience as an executive market president leading market turnarounds, he helps organizations build client-centered business development strategies and turn insight into measurable action. Larry is a two-time Amazon bestselling author and a lead business development instructor at the Graduate School of Banking at Colorado.